Specialist real estate debt advisory
Development Finance Since 2004
Property development finance from £500,000 for new-build housing, conversions and commercial development. Access to 300+ lenders, alongside family offices and real estate funds.
Discuss your deal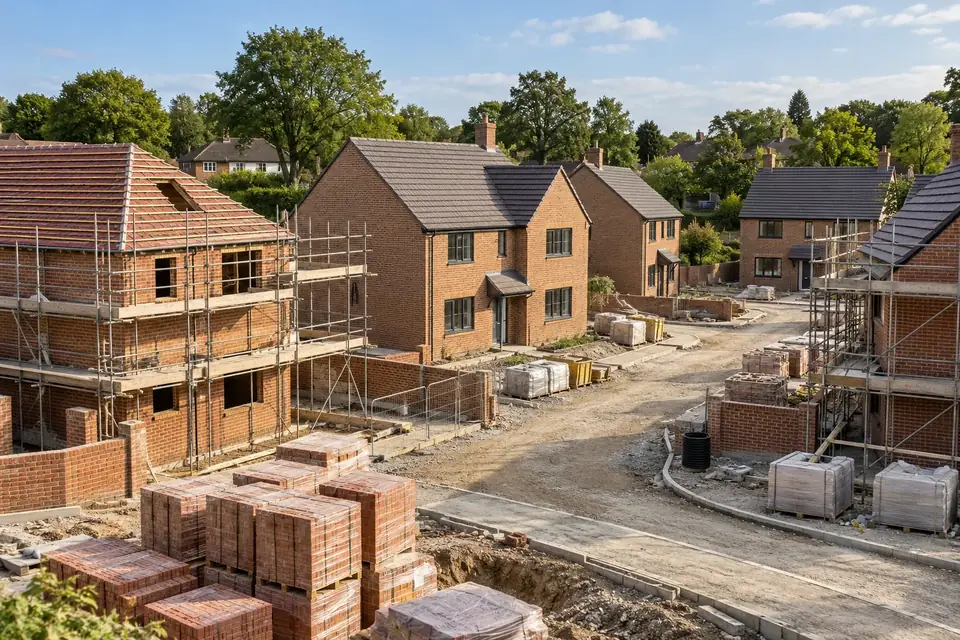
Request a call back
We respond within one business hour, Monday–Friday, 8am–6pm.
The finance
The funding parameters.
Residential development finance
New-build housing, apartments and conversions.
- Loan to cost · up to
- 90%
- Loan to GDV · up to
- 75%
- Rates from
- BBR + 3.99% p.a.
- Terms up to
- 48 months
- Location
- UK & selected Western European markets
Commercial development finance
Commercial property and mixed-use schemes.
- Loan to cost · up to
- 85%
- Loan to GDV · up to
- 65%
- Rates from
- BBR + 5% p.a.
- Terms up to
- 48 months
- Location
- UK & selected Western European markets
Indicative lender-panel parameters, subject to the scheme, borrower, valuation and exit. Maximum leverage, minimum pricing and longest term are not necessarily available together. Fees and other costs apply. BBR means Bank of England base rate. GDV means gross development value.
Leading specialist broker
Development finance advisory.
Our team of experts carefully examine every aspect of the deal, structuring each loan on a bespoke basis, so you can achieve the best chance of a successful financing outcome.
We constantly strive to add value, using our in depth knowledge of the development finance markets, negotiating with lenders, driving down fees, and promoting the merits of your project every step of the way.
Lender selection
Access to a panel of 300+ lenders, alongside family offices and real estate funds. We select the appropriate lenders for the transaction.
Terms and execution
We structure the submission, negotiate terms and fees, and remain involved through valuation, underwriting and legal completion.
Selected transactions
Development finance case studies
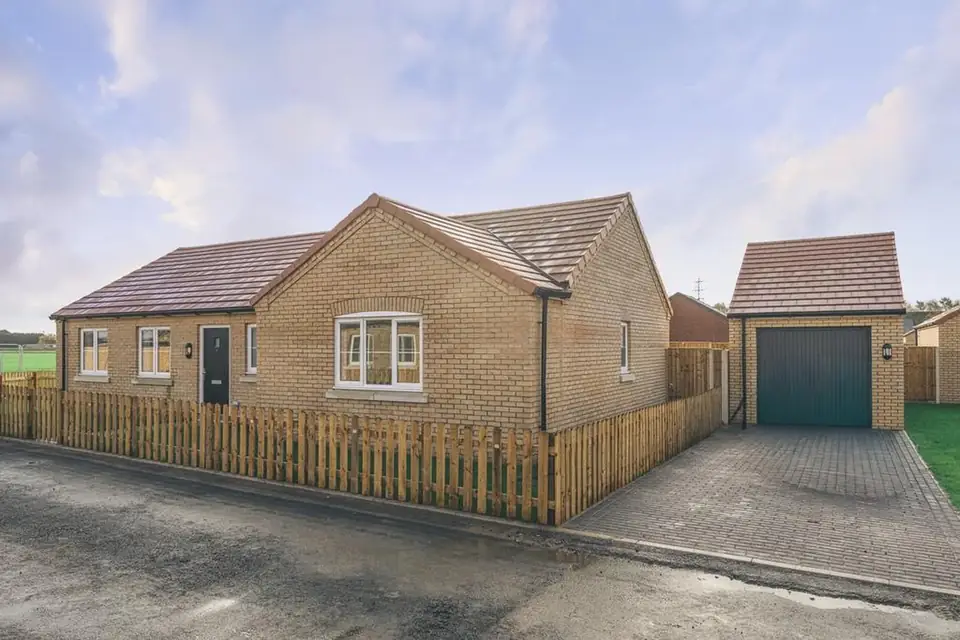
£13.9m
Residential developmentWisbech, Cambridgeshire
Lender: Sancus
First-phase funding for a consented 117-unit scheme. Matthew Dailly introduced the transaction and worked with the lender and development team to address rising construction costs and contractor delays.
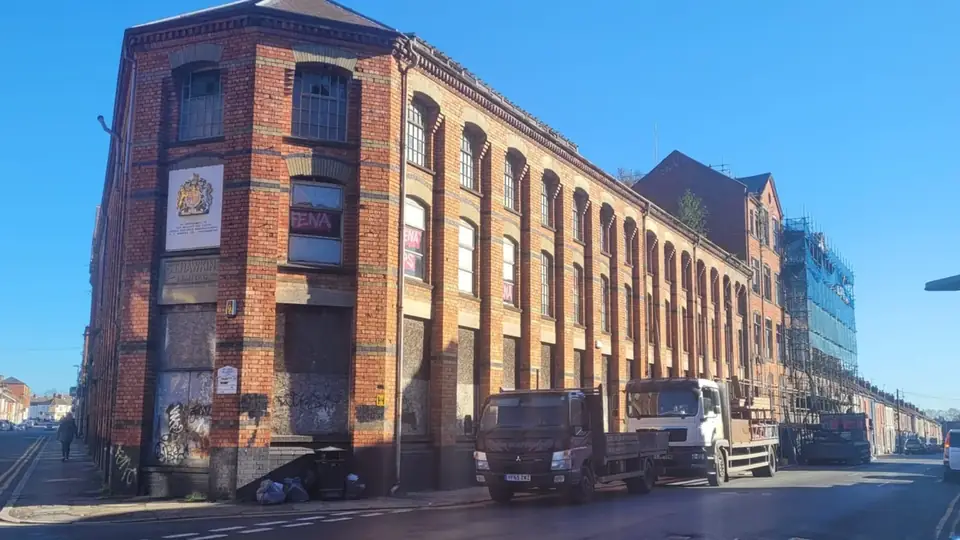
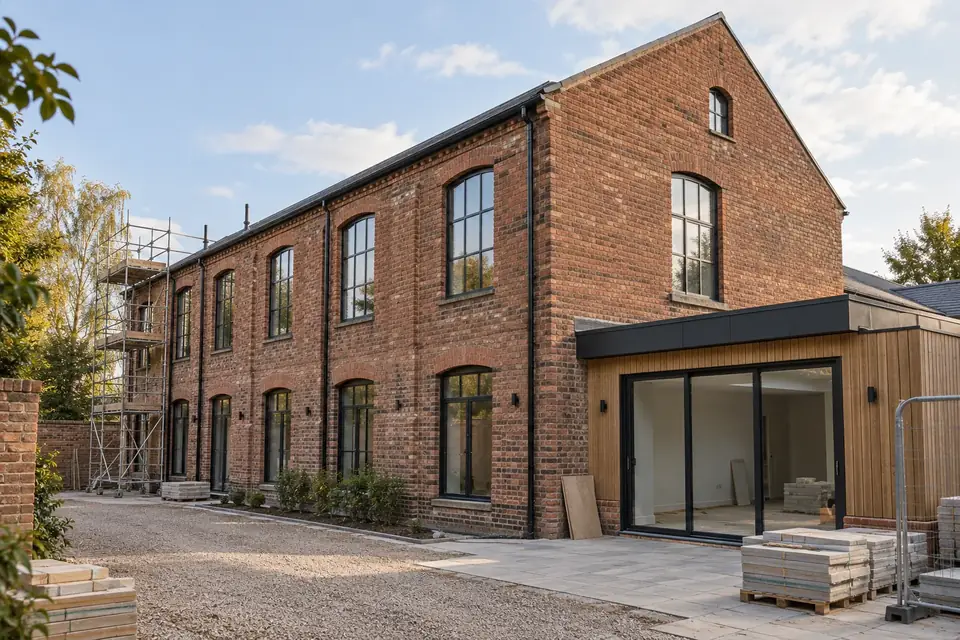
£9m
Listed-building conversionNorthampton
Lender: Octopus Real Estate
A 24-month facility for the conversion of the Grade II-listed G.T. Hawkins factory into 89 apartments. Matthew Dailly handled the transaction, selecting a lender prepared to fund the industrial conversion.
Historic transactions as reported by Development Finance Today. Facility terms relate to those transactions.
Lending detail
Lending criteria & facility structure.
Residential
Housing & conversions
For residential development lending, lenders consider the developer’s experience and credit profile, local demand, land and build costs, GDV and the exit plan.
Funding may cover new-build housing, apartments, build-to-sell or build-to-rent schemes, and conversions or changes of use. For ground-up schemes, facilities can fund site acquisition followed by staged drawdowns against completed and certified works.
Commercial
Commercial & mixed-use
Facilities include offices, hotels, industrial property and mixed-use schemes. Many lenders require an identified exit, such as agreed lettings, an operator or a strong covenant.
Senior investment loans may also be available. Hotels, care homes, student accommodation, co-living, retirement living and holiday lets require specialist lender appetite. The exit value can depend on trading performance or an operator covenant as well as the property value.
Facility size, planning and completion
Loan size and borrower contribution
The facility depends on developer experience, credit profile, net worth, available equity, land and build costs, GDV, the type of scheme and the strength of the exit.
For residential schemes, the indicative range is 65–75% of GDV and up to 90% of build cost. However, if additional security is provided, this can increase to 100%. The borrower contribution is typically 10–30% of total scheme cost; the value of an owned site may satisfy part of that requirement. These are alternative, conditional measures, not a guarantee that every maximum can be combined.
Planning, land and specialist property
Planning requirements depend on the facility and scheme. Construction loans are generally conditional on the necessary consents; site acquisition or planning-related bridging may be considered separately.
Sites without planning, or with only the prospect of consent, attract a smaller lender pool and lower leverage. Hotels, care homes, student accommodation, co-living, retirement living and holiday-let schemes require lenders whose appetite reflects the asset, its operation and the exit.
Timing and exit requirements
Some loans can be arranged in 4 weeks, but typically, for larger ground up schemes, it is more common to be 8–12 weeks for completion.
The repayment strategy must be supported by realistic sales, refinance or lease assumptions. It may involve individual unit sales, sale of the whole scheme, refinancing or agreed commercial lettings.
Contractor capability and financial standing, a credible appraisal, and a solicitor able to meet the timetable are material to execution.
The development case
Development appraisal and lender assessment.
End values and demand
For larger schemes, a feasibility study should assess the local market and the factors affecting viability. The proposed accommodation, end values and sales assumptions need to reflect demand in that location.
Build costs and contingency
Lenders assess construction costs against local labour and material costs, even where the developer’s own arrangements are cheaper. The appraisal should use conservative figures and provide for contingency, including the costs a lender could face if it had to take over the project.
Construction and sales period
The facility term needs to allow for both construction and sales, including delays. A funding structure that relies on a refinance in the final stages of the works introduces a further execution risk.
The main contractor
A contractor who can deliver on time and on budget is central to a smooth drawdown process.
As well as the developer’s experience, the lender will assess the main contractor’s capability and financial standing. The assessment includes:
- Experience in the type of project proposed and schemes of comparable size.
- Relevant experience of the site constraints, including period buildings, barn conversions, party walls or inner-city construction.
- Three years of profitable accounts and a sound balance sheet.
- Sufficient cash flow to fund one or two months of costs if required.
Evidence for the repayment route
- Unit sales
- The sales programme may include off-plan marketing, a show home or pre-sales to a housing association or specialist purchaser. The timing and value of those receipts should be reflected in the appraisal.
- Refinance
- Where refinance is the intended exit, the development lender may require a decision in principle or an offer letter to establish that the replacement facility is viable.
- Commercial letting
- For a development intended to be occupied by a hotel operator or commercial tenant, the lender may require a contract, letter of intent or lease agreement to support the exit.
Planning and contingency
Use conservative figures for GDV, build costs and timescales. Lenders will not rely on optimistic assumptions, and a contingency of at least 5–10% on build costs is expected. Lenders will typically only approve a full construction facility once planning has been granted, though bridging can hold a site while you await the outcome.
Specialist advice
The construction finance market is diverse, and it takes a specialist broker to know how best to increase your likelihood of approval, and to alleviate a great deal of stress along the way.
For an initial assessment
Project information for lender assessment.
The development appraisal, planning position, borrower details and exit evidence form the lender submission. Provide the documents available; we will identify any further information required for the chosen lenders.
View the project information requirements
1 / Project & planning
- Executive summary
- A brief description of the project outlining what you are building, the timeline, costs, profit expectations and overall strategy.
- Planning status
- Documentation relating to planning consent or applications.
- Site plan & drawings
- Architectural plans, elevations and CGIs of the finished development.
- Technical reports
- Contamination, structural surveys, ground investigations or feasibility studies.
2 / Borrower & team
- Borrowing structure
- Details of the company or SPV borrowing money, including corporate structure and control.
- Personnel
- Names, details and ownership percentages of individuals behind the project.
- CVs & profiles
- Overview of the development team, experience and past project success.
3 / Appraisal & cashflow
- Appraisal & schedule
- Full cost breakdown, GDV, profit calculations and unit-by-unit details.
- Costs & cashflow
- Month-by-month cashflow and building cost breakdown.
- Assets & liabilities
- Summary of personal and corporate assets, liabilities and net worth.
- Credit checks
- Additional information regarding any past credit issues.
4 / Exit & valuation
- Marketing strategy
- How the completed units will be marketed, sold or let, including target markets and pricing.
- Sales or valuation
- Comparable sales or valuations supporting the proposed GDV.
- Proof of exit
- Evidence of the loan repayment strategy; sales, refinance or lease agreement.
Site acquisition or development exit?
Bridging can fund a site purchase or the period before planning consent. A development exit loan can refinance a completed scheme while units are sold; finish-and-exit funding can cover remaining works before sale or refinance.
Contact Tiger Financial
Discuss your
development.
Speak to us about the scheme, the funding requirement and the terms you need to achieve.
We respond within one business hour.
Monday–Friday, 8am–6pm.
Independent debt advisory for professional property investors and developers.